An inherited house can bring practical questions at an already difficult time. Who can make decisions about it? What should happen to the belongings? Is it worth preparing the house for a listing, or would a sale in its current condition fit better?
Start with the authority to act, then compare the work, costs and terms of your options. A family's preferred timetable matters, but it needs to fit the property's title and estate requirements.
This article provides general information, not legal, tax or financial advice. A Missouri attorney and qualified tax professional can help you understand your situation.
Confirm who can act for the property
Before signing a sales agreement, ask a Missouri probate attorney to confirm who has authority to sell and what approvals apply. Ask the title professional handling the transaction what documents will be needed for closing.
Missouri law provides different sources of sale authority. For example, an independent personal representative has statutory powers to sell estate property, subject to the law's conditions and any relevant restrictions in the will. Another provision addresses sale powers granted through a will. These are reasons to check the estate's actual circumstances rather than assume every inherited-house sale follows the same process. See Missouri section 473.810 and section 473.457.
Family agreement is useful, but it does not by itself establish who may sign. Keep questions about ownership, decision-making authority and required signatures separate from the family's discussion of price and timing.
Prepare a useful first conversation
Write down what you already know: the property's location, whether someone lives there, its general condition, and the questions you want answered. It is fine to identify information you do not yet have.
Your attorney or title professional may ask to review estate and property documents. Ask which records are needed, who should receive them and how to send them securely. Avoid putting death certificates, account numbers, private family contact lists or financial records into a general inquiry message.
A short question list can help:
- Who is authorized to discuss and sign a sale?
- What title or estate issues could affect timing?
- Who will coordinate access, belongings and communication?
- What information does each professional need next?
Compare sale options using the written terms
Compare an agent-assisted listing with any direct purchase offer you are considering. Ask what each route would require in your case, rather than relying on a headline price or a promised closing speed.
For a listing, discuss preparation, showings, any proposed repairs, compensation and other selling expenses. For a direct offer, ask whether the buyer expects repairs or a cleanout, what inspections or other conditions apply, and who would pay each closing expense.
Put the estimates side by side. Include the proposed price, costs, work you would take on, contingencies and timing assumptions. Ask what could change the offer or delay closing. An estimated net amount is useful only when you understand what has been included and what remains uncertain.
Do not assume that an as-is offer means no expenses, no disclosures or no remaining belongings to handle. Ask your attorney about applicable disclosure obligations, and make sure the agreement spells out the buyer's expectations.
Be clear about condition and belongings
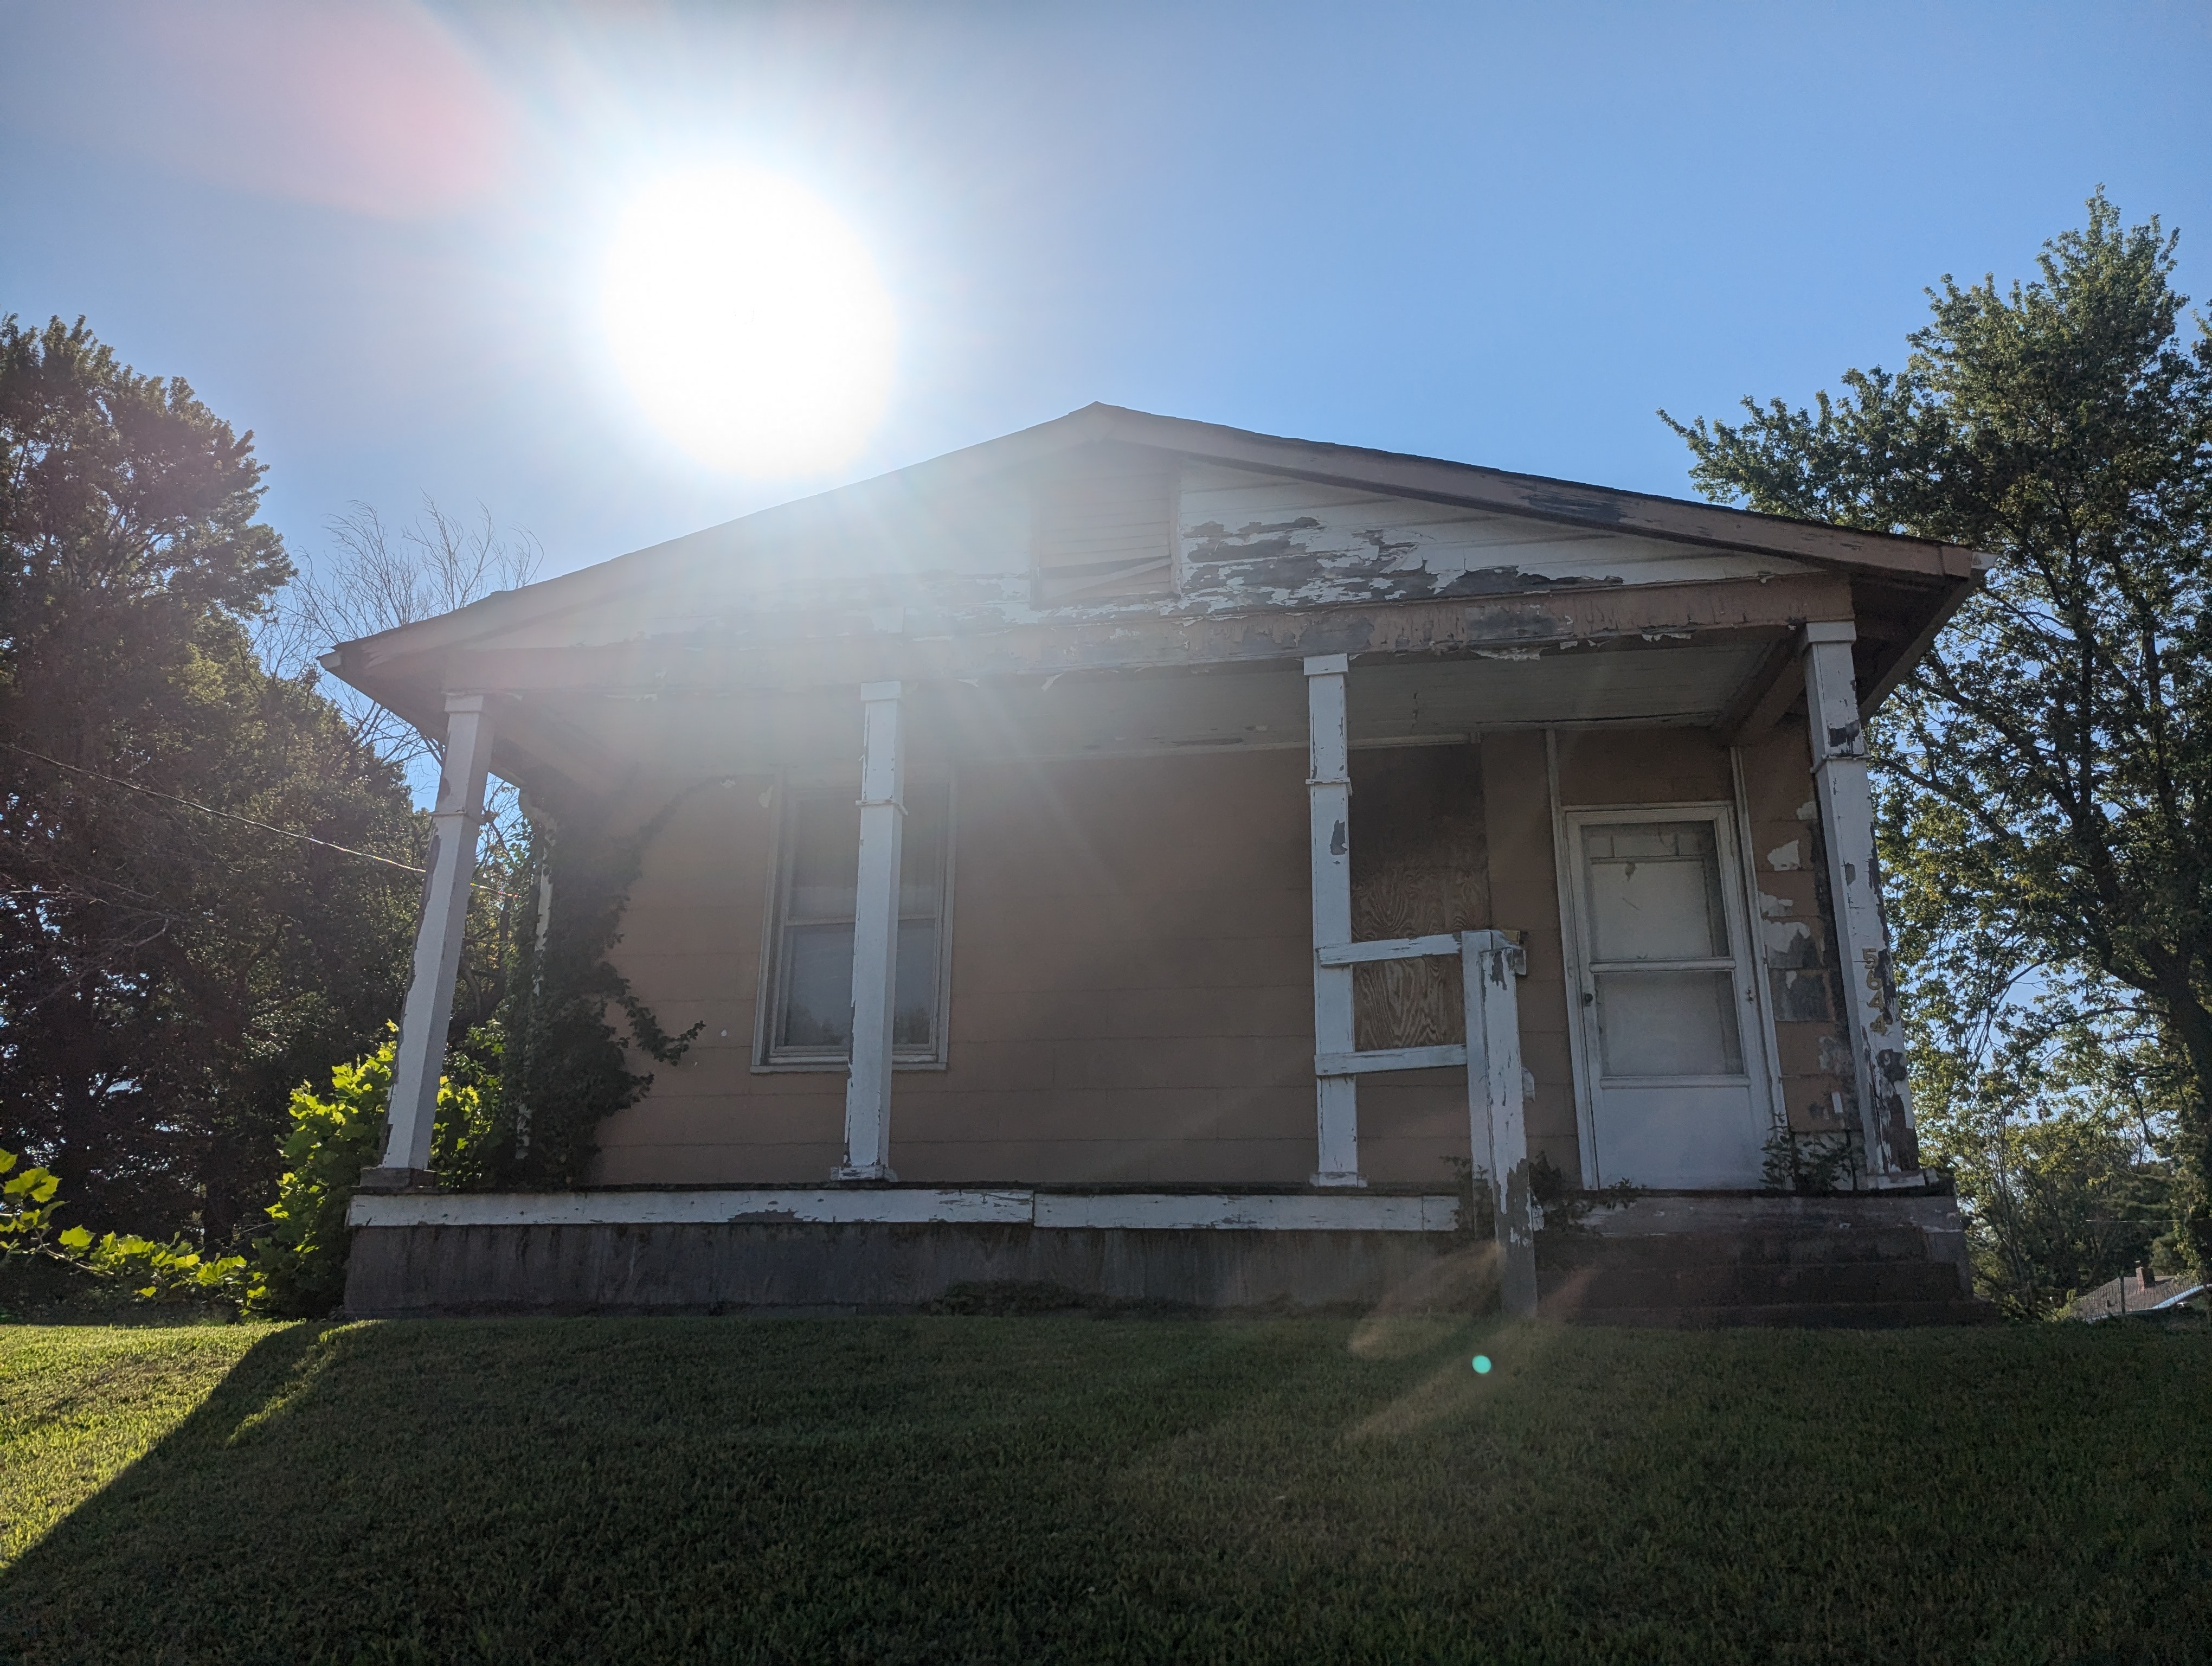
Describe what you know about the house accurately. If you have not lived there or inspected an area, say so instead of guessing. Separate a known problem from something that still needs assessment.
Before arranging a cleanout, agree on who has authority to make decisions about contents. Identify personal records and belongings the family wants to preserve. If a buyer is willing to take items left in the house, confirm that arrangement in writing.
If the house is vacant or its occupancy changes, ask the insurer what that means for coverage and any required precautions. Do not assume the existing arrangements suit the changed circumstances.
Discuss debt and taxes before estimating the proceeds
Estate obligations and a family member's personal liability are different questions. The Consumer Financial Protection Bureau explains that debts are generally paid from the estate; survivors generally are not personally responsible unless they shared responsibility or another exception applies. Ask counsel how this applies to the estate rather than assuming an heir must pay from personal funds. Read the CFPB explanation.
If there is a mortgage, ask the servicer and your attorney about the loan and the documentation needed to discuss it. Ask the closing professional for an estimate of transaction expenses and amounts that may need to be resolved. Do not treat an offer price as the amount available for distribution.
Tax basis also matters. The IRS explains that inherited property's basis is generally tied to its fair market value at death, with alternate valuation rules and exceptions in some circumstances. That does not make every later sale tax-free. Have a tax professional review the applicable basis and possible reporting obligations. Read the IRS guidance on inherited-property sales.
Choose the next step you can verify
You do not have to settle every question in one conversation. Start by confirming who can act, identifying the property's needs and requesting clear written terms for any sale option you are considering.
If you are considering St. Louis Cash Buyers, use the property inquiry form on its homepage to start a conversation. Ask about the proposed terms for your property and compare them with your other options. Keep legal and tax questions with the appropriate professionals, and agree on timing only after the relevant requirements are understood.