A house can be worth selling even when it is not ready for open houses, repairs, showings, or months of uncertainty. The direct home purchase versus listing decision is not simply about getting a house sold fast. It is about deciding which path fits your property, your timeline, and the amount of work you are willing or able to take on.
For some St. Louis-area owners, a traditional listing is the better financial move. For others, especially heirs, landlords with a difficult rental, or owners facing major repairs, a direct sale may offer more certainty and less disruption. The useful question is not which option is always best. It is what you keep, what you give up, and what matters most right now.
Direct Home Purchase Versus Listing: The Basic Difference
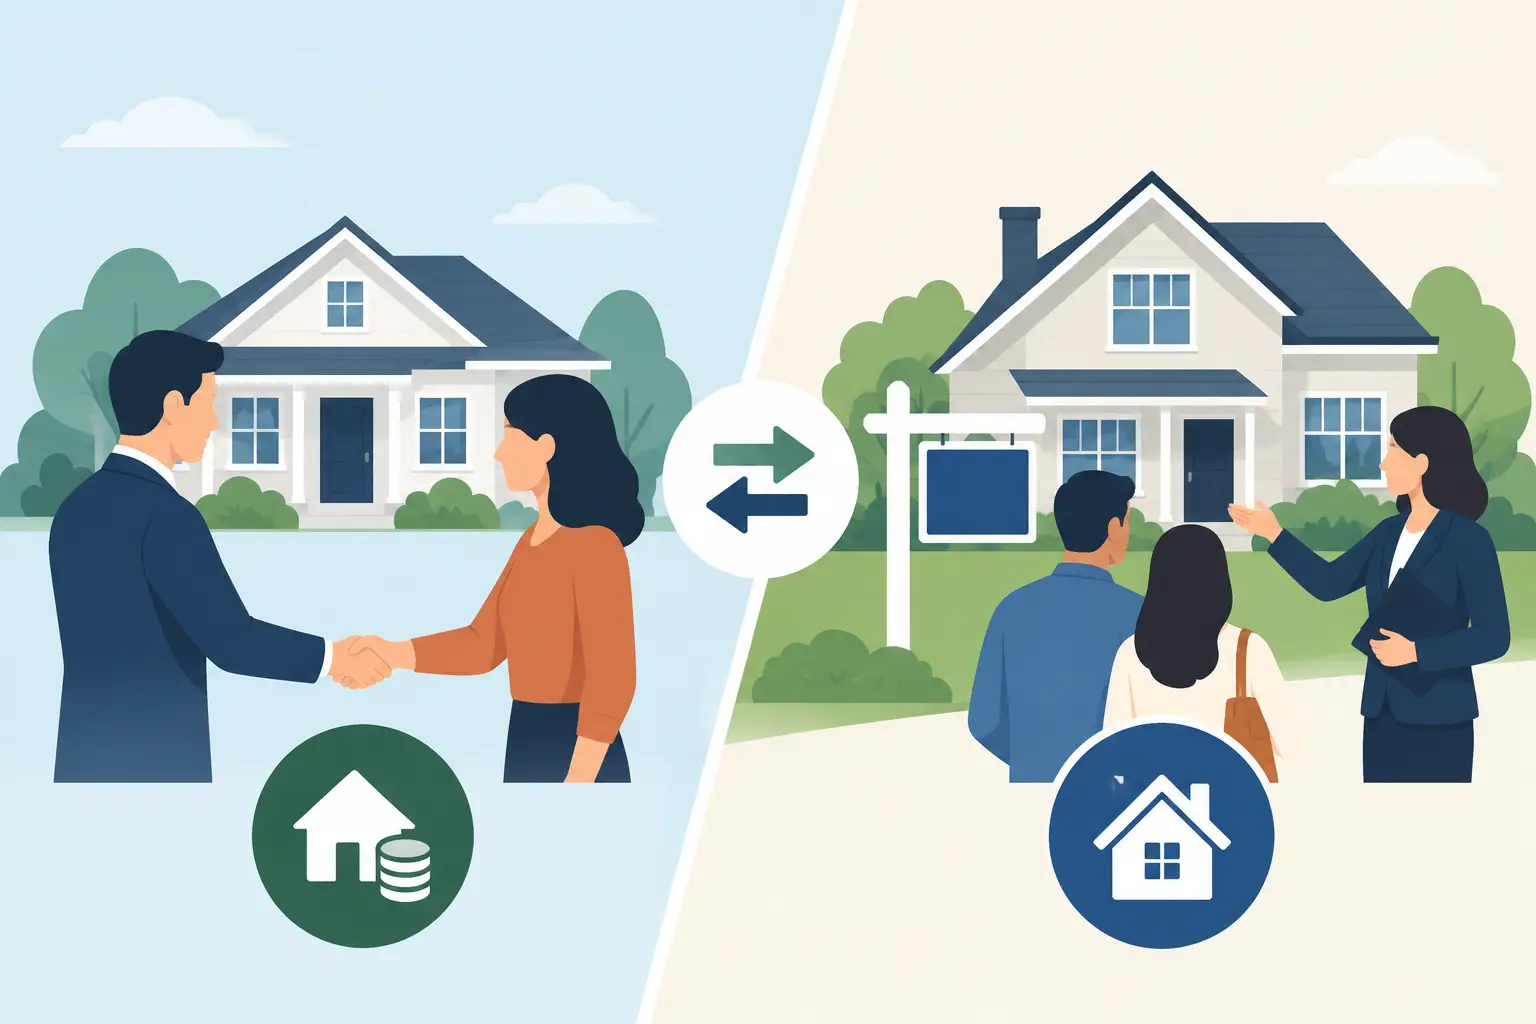
A traditional listing puts your home on the market through a real estate agent. The goal is to reach as many qualified buyers as possible and negotiate the strongest terms available. That process can produce a higher sale price, particularly when the property is clean, market-ready, and in an area with strong buyer demand.
A direct home purchase is different. You speak directly with a buyer who evaluates the property and may make an offer without placing it on the MLS. A direct buyer is not acting as your listing agent. If you agree to terms, the sale is handled as a purchase rather than a marketed listing.
The tradeoff is straightforward: a listed home may have more exposure and price upside, while a direct sale can reduce preparation, showings, and uncertainty. Neither route removes the need to read the paperwork carefully, understand the terms, and make sure the buyer or agent is a fit for your situation.
When Listing May Make More Sense
If your house is in good condition, you have time to prepare it, and getting the highest possible market price is your main goal, listing deserves serious consideration. An agent can help position the home, coordinate marketing, manage showings, and negotiate with buyers.
This route may be especially worthwhile when you can address small issues before going on the market. Fresh paint, basic cleanup, landscaping, and minor repairs can affect buyer interest. A home that is vacant, clean, updated, and easy to show often has more choices in the buyer pool.
Still, the list price is not the amount you take home. Before choosing this route, ask an agent to walk you through likely commissions, seller concessions, repair requests, staging or preparation costs, and expected closing costs. Ask what happens if an inspection reveals a concern with the roof, foundation, plumbing, electrical system, or sewer lateral.
A listing also requires some flexibility. Buyers may request showings with limited notice. A buyer's loan approval can take time, and an accepted contract can still change if financing, appraisal, inspection, or title issues arise. Those are normal parts of many real estate transactions, but they may not work well for every seller.
When a Direct Purchase May Fit Better
A direct purchase can be worth exploring when the property needs more than a light touch-up or when the usual listing process would create a real burden. That might include an inherited house filled with belongings, a vacant property that needs attention, or a rental where tenants, repairs, and showings are difficult to coordinate.
It may also help to explore this option if you are relocating, dividing property during a divorce, managing a house after a death in the family, or dealing with damage from water, fire, or deferred maintenance. You do not need to have every detail solved before asking what options might be available.
With a direct buyer, the property is commonly evaluated in its current condition. That can mean no required cleaning, repairs, staging, or repeated showings before an offer discussion. Terms vary by property and agreement, so confirm exactly what the buyer is taking on and what, if anything, you would still need to handle.
A direct sale can also offer more control over timing. Some owners need extra time to move belongings. Others want a shorter closing window. A buyer may be able to discuss a closing date that works for both sides, but no timeline should be assumed until the property is reviewed and terms are agreed in writing.
Compare the Net Result, Not Just the Offer Price
The highest number on paper is not automatically the best result. Compare what you expect to receive after the costs, work, risk, and time tied to each option.
With a listing, you may receive a higher purchase price, but you could also have agent commissions, preparation expenses, repair negotiations, buyer credits, and holding costs while the home is being marketed. Holding costs can include mortgage payments, property taxes, insurance, utilities, maintenance, and the practical cost of keeping a vacant house secure.
A direct offer may be lower because the buyer is accounting for repairs, resale risk, and the work of owning the property after closing. In return, the arrangement may avoid agent commissions and may reduce the need for repairs or cleanup. Do not fill in the blanks yourself. Ask for the offer terms in writing and compare them line by line with a realistic listing estimate.
If there is little or no equity, the decision needs even more care. A sale price alone does not show whether existing loans, liens, taxes, or other obligations can be paid at closing. A title company can identify title-related issues, and a qualified attorney, tax professional, or other appropriate advisor can help with questions beyond the sale itself.
Questions to Ask Before You Choose
A pressure-free conversation should leave you clearer, not rushed. Whether you talk with an agent or a direct buyer, ask questions that reveal the real process.
- What would I likely need to repair, clean, remove, or disclose before closing?
- Which fees, commissions, taxes, or closing costs could affect my proceeds?
- What conditions must be met before the sale can close?
- How will title concerns, liens, heirs, tenants, or a mortgage be handled?
- Can I choose a closing date, and what happens if my timing changes?
For an inherited property, confirm who has authority to sell before making commitments. For a rental, review the lease, tenant status, deposits, and access arrangements. For a property with significant damage, be direct about what you know. Clear information helps you receive a more realistic answer and prevents unpleasant surprises later.
A Simple Way to Evaluate a Direct Offer
Start by sharing the address, the home's condition, any known repair concerns, and your preferred timing. An initial conversation is not a signed agreement, and it does not obligate you to sell. It simply helps determine whether a direct purchase may be realistic for the property.
If an offer is presented, take time to review the purchase price, earnest money, inspection or contingency language, closing date, who pays which costs, and what happens with personal property left behind. If anything is unclear, ask. You can also have an attorney or trusted advisor review documents before you sign.
Then compare that offer against the likely net result and effort of listing. If the home is ready for buyers and you have room in your schedule, listing may be the stronger choice. If the home needs substantial work or you value a simpler as-is path, a direct purchase may be worth accepting even if it is not the highest possible gross price.
The Right Sale Is the One You Can Live With
Selling a house is rarely just a math problem. The right decision may depend on whether you have the money and energy for repairs, whether the property is creating stress, how quickly you need to move, and how much uncertainty you can reasonably carry.
You do not have to choose between pretending the house is perfect and giving it away. Gather clear information, compare realistic outcomes, and choose the terms that fit your life. Explore your selling options with St. Louis Cash Buyers. Tell us about your property - no pressure, no obligation.